skip to main content
MMBB
MMBB Supporting Your Calling is Our Calling MonitorMMBB Supporting Your Calling is Our Calling
TOMORROW

MMBB Offers Option for Roth 403(b) Contributions

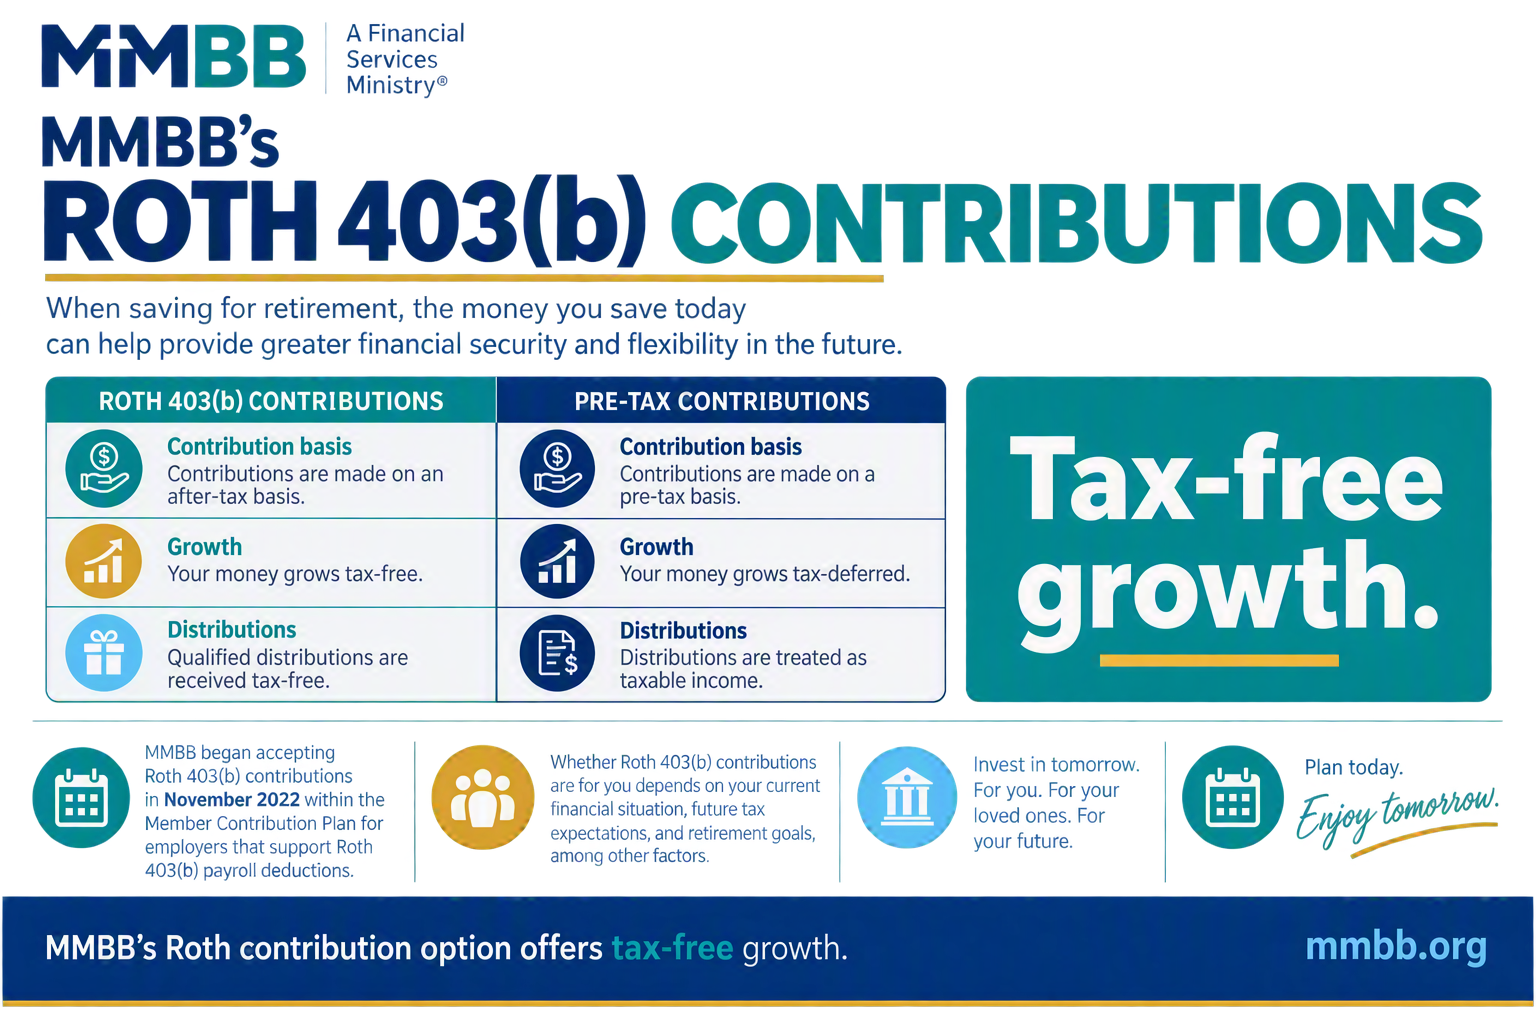
Roth 403(b) contributions allow contributions to be made on an after-tax basis; your money grows tax-free and then qualified distributions are received tax-free. With pre-tax premiums, you make contributions on a pre-tax basis, your money grows tax-deferred, and distributions are treated as taxable income.

MMBB Offers Option for Roth 403(b) Contributions
4 minute read

by MMBB Financial Services Director William Watko

What's in this Article?

  • Pros and Cons of a Roth 403(b) Contributions
  • Should I Consider Roth Contributions?

Famous investor and philanthropist Warren Buffett, often referred to as the "Oracle of Omaha," once observed, "Someone's sitting in the shade today because someone planted a tree a long time ago." That sentiment perfectly captures the value of retirement planning. The money you save today can help provide greater financial security and flexibility in the future.

Roth 403(b) contributions allow contributions to be made on an after-tax basis; your money grows tax-free and then qualified distributions are received tax-free.  With pre-tax premiums, you make contributions on a pre-tax basis, your money grows tax-deferred, and distributions are treated as taxable income.

MMBB began accepting Roth contributions in November 2022 within the Member Contribution Plan for employers that support Roth payroll deductions. Not all employers have the infrastructure to accommodate Roth contributions, so it is important to check with your employer if this is an option you are considering.  Participants in MMBB's Member Contribution Plan can choose the amount deducted from each paycheck for a Roth contribution, and their employer may contribute if the plan permits. Because Roth contributions are made after taxes are withheld, qualified earnings can be withdrawn tax-free.

Pros and Cons of a Roth Premiums

Roth contributions have no income limits or vesting requirements, though standard 403(b) contribution limits apply. If you contribute to multiple 403(b) accounts, coordinate your contributions to stay within those limits. In 2026, employees may defer up to $24,500 in salary, with an additional $8,000 catch-up contribution available to those age 50 to 59. Members ages 60 to 63 qualify for an enhanced catch-up amount.  Employees with 15 years of service in an eligible field may qualify for an additional catch-up contribution.  SECURE 2.0 requires 2026 catch-up premiums to be on a Roth basis if the member’s FICA wages exceeded $150,000 for 2025.

Earnings may be withdrawn tax-free after a distributable event if the account has been open for more than five years and you are age 59½, disabled, or the beneficiary of the deceased. Nonqualified distributions may be subject to taxes and, in some cases, a 10% additional tax unless an exception applies.

The tax-free earnings are ideal for individuals who expect their tax rates to rise over time, meaning the earlier you can begin investing in Roth contributions, the better. As contributions are made on an after-tax basis, your taxable income will not be reduced as it would for traditional pre-tax premiums. Since you are paying taxes on contributions at a lower rate now, the tax-free withdrawals later when your income and tax rates may be higher can be an enticing draw to choose this option. However, this is operating under the assumption that tax rates will remain favorable in the future. If they fall, the benefits of tax-free withdrawals may decrease with them. 

Within the 403(b) plan, Roth accounts do not require account holders to take mandatory minimum distributions starting at age 73. Such flexibility can be valuable if you want to preserve your savings for as long as possible or pass them on to your heirs. This can be an intriguing estate planning tool since your funds will grow tax-free for your beneficiaries. 

Should I Consider Roth 403(b) Contributions?

Whether Roth contributions are for you depends on your current financial situation, future tax expectations, and retirement goals.  Consider whether you prefer to pay taxes on your retirement savings now or later and factors such as:

  • Your age
  • The number of years until retirement
  • Your current tax rate and need for tax relief
  • Your projected tax rate in retirement, including taxable pension and Social Security income
  • The possibility of fewer tax deductions in retirement and your projected investment earnings
  • Your current retirement portfolio. If you have already accumulated significant tax- deferred savings, contributing to a Roth plan will help diversify your portfolio and may give you greater flexibility in retirement.
  • Your long-term plan to remain in public service 

Before making a decision, carefully evaluate all available options. Because the rules governing Roth accounts can be complex, MMBB encourages members to consult a financial planning specialist before making a choice. An MMBB financial planning specialist can help members understand how MMBB’s Roth option fits into their overall retirement strategy and long-term financial goals. Remember, as an MMBB member, you have access to these services at no additional cost.


William Watko has been MMBB Financial Services Director since 2016. His previous roles include management positions at Xerox, Mellon Financial and PricewaterhouseCoopers. Bill earned his bachelor’s degree from the University of Chicago and a master’s degree from Boston University. 

Sources:

  1. https://smartasset.com/retirement/roth-403-b

The information contained herein is for informational purposes only.  While MMBB made every attempt to ensure that the information is accurate, MMBB is not responsible for any errors or omissions or the results obtained from the use of this information.  MMBB is not liable for any success or failure that is directly or indirectly related to the use of the information contained herein.  The information contained herein does not constitute any financial, insurance, investment, legal, or tax advice.  The inclusion of any third party links does not constitute an endorsement. In no event shall, MMBB and/or its fiduciaries, directors, officers, employees, or agents thereof be liable for any special, direct, indirect, consequential, or incidental damages or any damages whatsoever, whether in action of contract, negligence or tort, arising out of or in connection with the use of the information contained herein.

This article is available in audio format through our text-to-speech feature for accessibility and convenience. The text-to-speech feature is generated using artificial intelligence. While we strive for an accurate listening experience, this information may be incomplete or inaccurate. Please refer to the written version as the official source of content. This content should not be relied upon as a substitute for professional advice.

Images displayed in this material were created in whole or in part by generative artificial intelligence (AI) and are provided for illustrative purposes only. They may contain errors or inaccuracies and should not be relied upon as a substitute for professional advice. They are not intended to represent real individuals, organizations, or events.

What's the takeaway?

Resources for church finances and administration, clergy compensation & taxes, personal finance and financial wellness.

Translations of any materials into languages other than English are intended solely as a convenience to the non-English-reading public. We have attempted to provide an accurate translation of the original material in English, but due to the nuances in translating to a foreign language, slight differences may exist.

Las traducciones de cualquier material a idiomas que no sean el inglés son para la conveniencia de aquellos que no leen inglés. Hemos intentado proporcionar una traducción precisa del material original en inglés, pero debido a las diferencias de la traducción a un idioma extranjero, pueden existir ligeras diferencias.

Close Alert

You will be linking to another website not owned or operated by MMBB. MMBB is not responsible for the availability or content of this website and does not represent either the linked website or you, should you enter into a transaction. The inclusion of any hyperlink does not imply any endorsement, investigation, verification or monitoring by MMBB of any information in any hyperlinked site. We encourage you to review their privacy and security policies which may differ from MMBB.

If you “Proceed”, the link will open in a new window.

back to topBack to Top