by MMBB Financial Services Director William Watko
Famous investor and philanthropist Warren Buffett, often referred to as the "Oracle of Omaha," once observed, "Someone's sitting in the shade today because someone planted a tree a long time ago." That sentiment perfectly captures the value of retirement planning. The money you save today can help provide greater financial security and flexibility in the future.
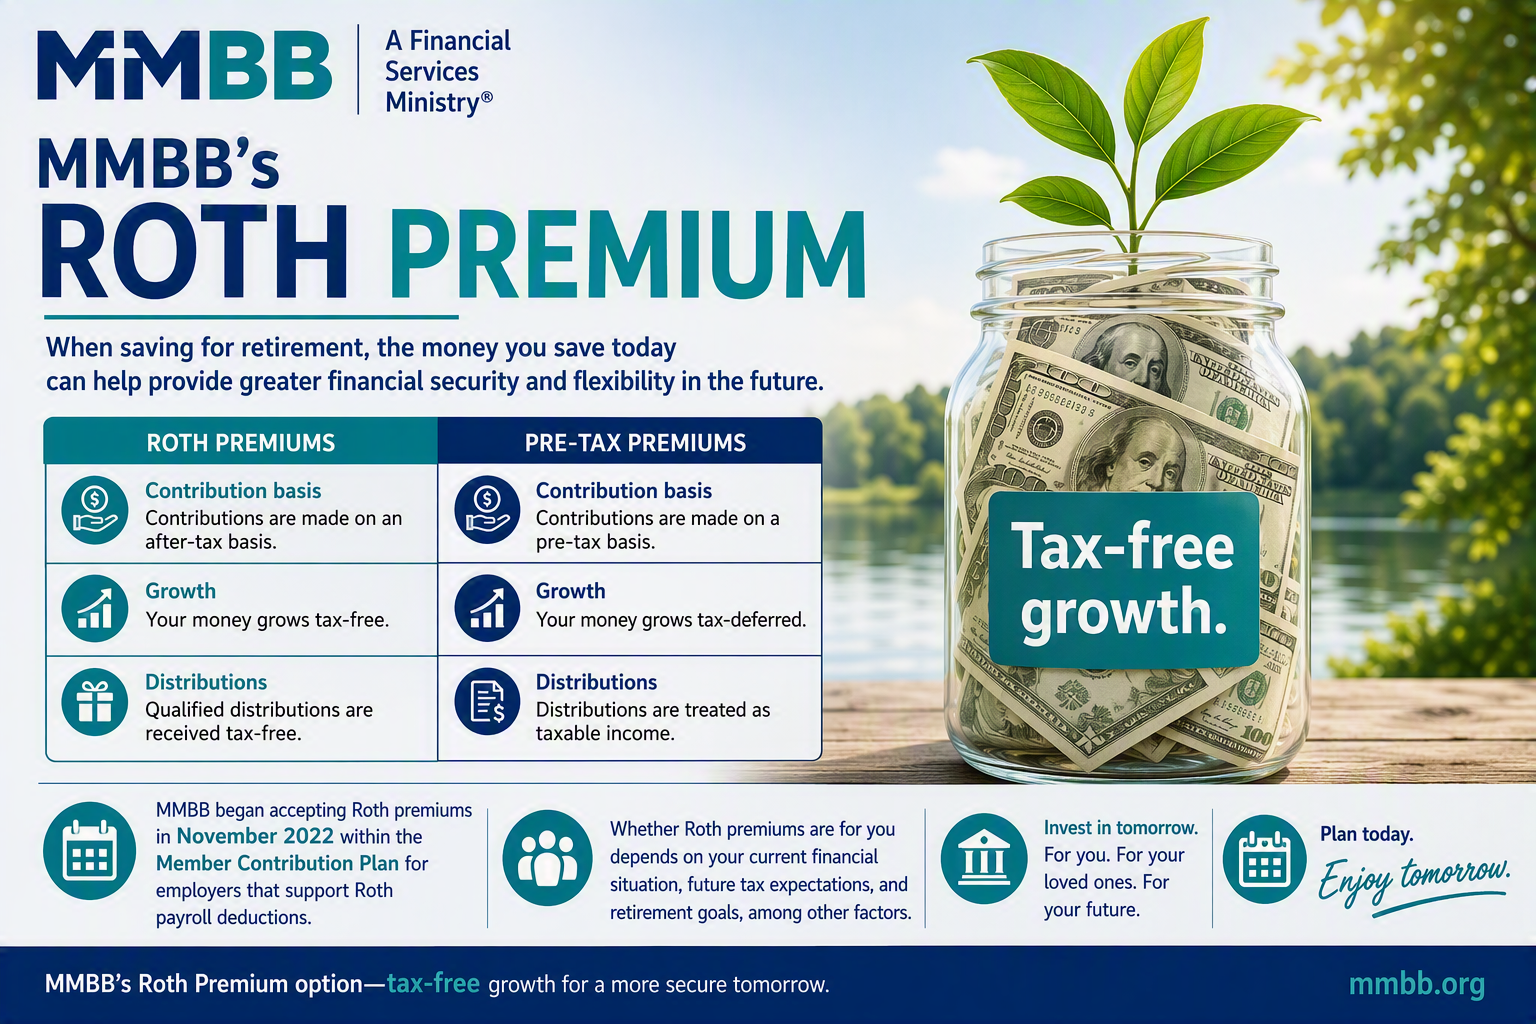
Roth premiums allow contributions to be made on an after-tax basis; your money grows tax-free and then qualified distributions are received tax-free. With pre-tax premiums, you make contributions on a pre-tax basis, your money grows tax-deferred, and distributions are treated as taxable income.
MMBB began accepting Roth premiums in November 2022 within the Member Contribution Plan for employers that support Roth payroll deductions. Not all employers have the infrastructure to accommodate Roth contributions, so it is important to check with your employer if this is an option you are considering. MMBB Member Contribution Plan participants can choose the amount deducted from each paycheck for a Roth premium, and their employer may contribute if the plan permits. Because Roth premiums are made after taxes are withheld, qualified earnings can be withdrawn tax-free.
Pros and Cons of a Roth Premiums
Roth premiums have no income limits or vesting requirements, though standard 403(b) contribution limits apply. If you contribute to multiple 403(b) accounts, coordinate your contributions to stay within those limits. In 2026, employees may defer up to $24,500 in salary, with an additional $8,000 catch-up contribution available to those age 50 to 59. Members ages 60 to 63 qualify for an enhanced catch-up amount. Employees with 15 years of service in an eligible field may qualify for an additional catch-up contribution. SECURE 2.0 requires 2026 catch-up premiums to be on a Roth basis if the member’s FICA wages exceeded $150,000 for 2025.
Earnings may be withdrawn tax-free after a distributable event if the account has been open for more than five years and you are age 59½, disabled, or deceased. Nonqualified distributions may be subject to taxes and, in some cases, a 10% additional tax unless an exception applies.
The tax-free earnings are ideal for individuals who expect their tax rates to rise over time, meaning the earlier you can begin investing in Roth premiums, the better. As contributions are made on an after-tax basis, your taxable income will not be reduced as it would for traditional pre-tax premiums. Since you are paying taxes on contributions at a lower rate now, the tax-free withdrawals later when your income and tax rates may be higher can be an enticing draw to choose this option. However, this is operating under the assumption that tax rates will remain favorable in the future. If they fall, the benefits of tax-free withdrawals may decrease with them.
Within the 403(b) plan, Roth accounts do not require account holders to take mandatory minimum distributions starting at age 73. Such flexibility can be valuable if you want to preserve your savings for as long as possible or pass them on to your heirs. This can be an intriguing estate planning tool since your funds will be growing tax-free for your beneficiaries.
Should I Consider Roth Premiums?
Whether Roth premiums are for you depends on your current financial situation, future tax expectations, and retirement goals. Consider whether you prefer to pay taxes on your retirement savings now or later and factors such as:
- Your age
- The number of years until retirement
- Your current tax rate and need for tax relief
- Your projected tax rate in retirement, including taxable pension and Social Security income
- The possibility of fewer tax deductions in retirement and your projected investment earnings
- Your current retirement portfolio. If you have already accumulated significant tax- deferred savings, contributing to a Roth plan will help diversify your portfolio and may give you greater flexibility in retirement.
- Your long-term plan to remain in public service
Before making a decision, carefully evaluate all available options. Because the rules governing Roth accounts can be complex, MMBB encourages members to consult a financial planning specialist before making a choice. An MMBB financial planning specialist can help members understand how MMBB’s Roth option fits into their overall retirement strategy and long-term financial goals. Remember, as an MMBB member, you have access to these services at no additional cost.
Sources:
- https://smartasset.com/retirement/roth-403-b
William Watko has been MMBB Financial Services Director since 2016. His previous roles include management positions at Xerox, Mellon Financial and PricewaterhouseCoopers. Bill earned his bachelor’s degree from the University of Chicago and a master’s degree from Boston University.